
Barclays US
- Rating
- 4.6
- Downloads
- 1.00M
- Content Rating
- Everyone
Barclays US - Screenshots
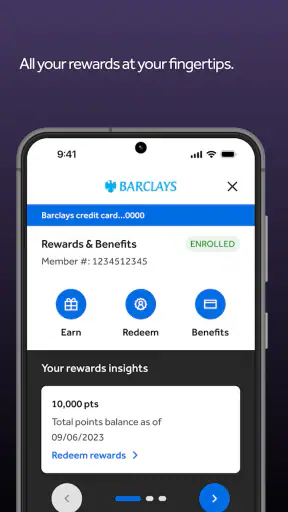
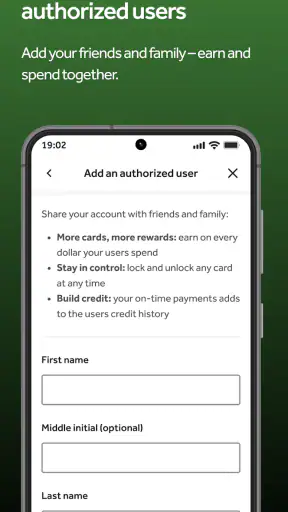
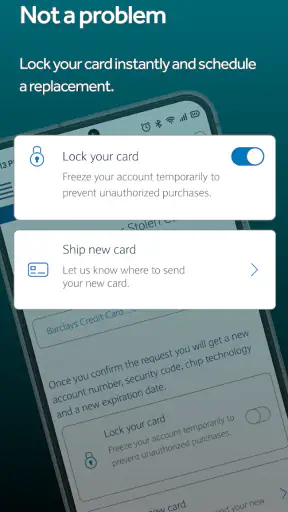
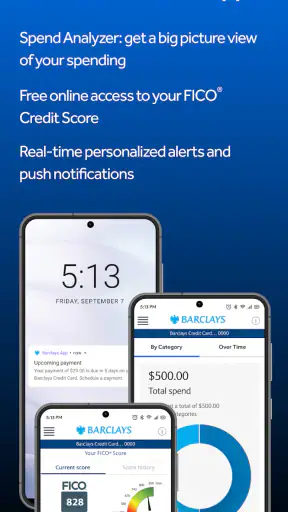
Pros
- Clear overview of balances
- transactions
- and recent account activity.
- Mobile check deposit saves time compared with visiting a branch.
- Card controls help lock or unlock a misplaced debit card quickly.
- Bill payment features make recurring payments easier to manage.
- Security alerts can help detect unusual account activity promptly.
Cons
- Some features may require enrollment or an eligible Barclays account.
- Customer support availability may vary by issue and time of day.
- App performance can depend heavily on your internet connection.
- Not all banking services may be available through the mobile app.
- Users may need extra verification when signing in from a new device.
Barclays US - Description
- App Name
- Barclays US
- Package Name
- com.barclaycardus
- Developer
- Barclays US
- Category
- Finance
- Last Updated
- Feb 16, 2012
- Version
- 8.7.2
Managing a credit card from a phone sounds ordinary until a payment is due, a purchase looks unfamiliar, or you need to check available credit while away from a computer. I spent time using Barclays US with that practical question in mind: does it become a dependable part of a monthly money routine, or does it only feel useful during the first few days? My answer is positive, with an important qualification. It works best for people who already use Barclays for their card activity and want a focused mobile account companion, rather than for anyone looking for a complete financial dashboard.
Barclays US is a free finance app from Barclays US for Android and iOS users. It is rated for Everyone, runs on devices using iOS or Android 12 and newer, and its current version is 8.7.2. The app has reached over a million installs, with an average rating of 4.6 from around 60 thousand ratings. Those figures suggest that it is not a niche utility used only occasionally; it has become a regular access point for many Barclays customers.
What the first week feels like
The first-week appeal comes from reducing the number of small steps between a question and an answer. Instead of waiting until I am near a laptop, I can open the app when I want to check card activity, review a recent transaction, or think through whether a purchase fits my available credit. That immediacy matters more than flashy extras in a finance app. The best mobile banking experience is often the one that lets me finish a task before I lose track of why I opened it.
I found the focused nature of Barclays US helpful. It is not trying to be a general-purpose budgeting suite, an investment terminal, and a bill organizer at the same time. Its role is narrower: give Barclays customers a convenient way to stay connected to their account. That makes the interface easier to approach when the only thing I need is an account check rather than a full financial review.
New users should expect the usual financial-app discipline during setup. Account access, authentication, and device security are not inconveniences I would try to bypass. They are part of the trade-off for handling sensitive information on a phone. I recommend setting it up when you have time to verify your details carefully, rather than during a rushed checkout or while travelling. A clean first login makes later quick checks much less frustrating.
One useful habit is to open the app immediately after a meaningful purchase instead of waiting for the end of the week. This is not because every transaction needs investigation. It is because early review helps separate a normal authorization from a genuinely unfamiliar charge while the context is still fresh. Barclays US is particularly practical in that moment: it gives the account holder a direct place to look instead of relying on memory or scattered email notifications.
The app also suits a simple pre-purchase routine. Before making a larger payment, I can check the account rather than guessing about available room. That does not replace a proper budget, but it prevents a common mistake: treating the credit limit as money that is automatically available for spending. The app is most valuable when used as a quick source of current account awareness, not as permission to spend more.
Its store summary, “Safe. Convenient. Rewarding.” captures the intended direction, but I would not judge it by that sentence alone. Convenience is the strongest part of the experience. The rewarding side depends on how the individual Barclays account is used and whether the customer actually pays attention to the account’s own benefits and activity. The app can make those details easier to revisit, but it cannot turn passive account use into a thoughtful money habit by itself.
Who benefits immediately
Barclays cardholders are the obvious audience. If your main need is mobile access to one Barclays relationship, the app has a clear purpose from the first session. It is also useful for people who travel between home, work, and family commitments and do not want account management tied to a desktop. A phone-based check can be enough to confirm that a payment or purchase is reflected as expected.
I can also see value for someone who shares household spending decisions but wants to keep account review personal and controlled. A quick look at recent activity can support a conversation about an upcoming payment without turning the whole household budget into a complicated project. That is a modest use case, but it is exactly the kind of recurring situation that determines whether a finance app stays installed.
The less suitable audience is someone seeking one place for several banks, detailed spending categories, long-term savings targets, and broad financial planning. Barclays US is not the natural replacement for a dedicated budgeting service or a multi-account aggregator. If your financial life is spread across many providers, a broader tool may save more time, even if you still keep this app for direct Barclays access.
Why it can remain useful after the novelty fades
The first week is about access; the following months are about repetition. A finance app earns lasting space when it supports routines that happen every billing cycle. Barclays US has a reasonable chance of doing that because account review is not a one-time task. Payments, purchases, available credit, and unfamiliar activity remain relevant long after the initial curiosity disappears.
My preferred monthly workflow is short. I check activity after the statement period, look for anything I do not recognize, confirm that the planned payment is realistic, and then close the app. This approach avoids turning every visit into an hour of financial administration. It also gives the app a defined job. When an app has a clear role in a routine, it is easier to maintain than one that demands constant attention without offering a clear decision in return.
A second workflow is useful around recurring charges. Subscriptions and automatic payments can quietly continue for months, so I would use the app to review the transaction history around the time those charges normally appear. The insight here is not merely “check your balance.” It is to compare the timing and description of repeat charges with what you expect. That makes the mobile account view a lightweight audit tool, even if it is not a full budgeting system.
For people who pay their card regularly, the app can act as a reminder to verify the account rather than as a place to spend more time. I prefer that kind of low-maintenance relationship. The goal is not to open a finance app for entertainment; it is to make a necessary task quick enough that I actually do it. Barclays US is strongest when it stays in that lane.
There is also a useful distinction between monitoring and planning. The app can support awareness of what is happening in the account, but awareness alone does not create a spending plan. I would pair it with a simple personal budget if I needed to control categories, prepare for irregular expenses, or track several accounts together. That combination is more realistic than expecting a card-management app to answer every financial question.
Where maintenance becomes work
The maintenance burden is relatively low, but it is not zero. Financial apps require users to keep their access details current, pay attention to security prompts, and install updates when needed. A phone that is shared, rarely updated, or protected by a weak passcode makes any account app less comfortable to use. The responsibility sits partly with the app and partly with the device owner.
I would also avoid treating notifications as a complete monitoring system. Alerts can be useful, but I still prefer opening the account and reviewing the actual activity periodically. A notification may draw attention to an event; it does not necessarily provide the full context needed to decide whether the event is expected. That extra check is a small maintenance task, yet it is the difference between seeing a message and understanding the account.
Another practical issue is device compatibility. The app requires iOS or Android 12 and newer, so anyone using an older phone or an outdated operating system should check that their device can run it before making the app central to their routine. This is not a complaint about the app’s purpose, but it is a real planning detail. Losing access because an old device cannot keep up is especially inconvenient when the app is used for time-sensitive account checks.
Updates can improve reliability and security, but they also create a small recurring obligation. I would keep automatic updates enabled when possible and avoid postponing them indefinitely. The trade-off is familiar: a little background maintenance in exchange for a more current banking tool. Users who dislike updating apps may find this more irritating than someone already accustomed to maintaining a modern phone.
The friction that may cause fatigue
The main source of fatigue is repetition without new insight. If I open Barclays US several times a day only to see the same account information, the habit can quickly feel unnecessary. The app is better suited to purposeful checks than constant refreshing. A sensible schedule—after important purchases, around payment time, and during a monthly review—keeps it useful without allowing it to become another source of financial anxiety.
Security steps can also feel slower when I am in a hurry. I consider that an acceptable trade-off for a finance app, but it still affects the real-world experience. Someone trying to confirm a purchase at a checkout may value speed more than someone reviewing an account at home. I would rather have a secure pause than an effortless account screen that makes access careless, yet the friction is worth acknowledging.
Another limitation is scope. Barclays US is not the best place to understand an entire household’s financial position when money is distributed across multiple banks, cards, loans, and savings products. In that situation, switching between apps may become tiring. A general budgeting platform can offer a broader view, while this app remains the more direct choice for Barclays-specific account access. The better option depends on whether direct control or all-in-one visibility matters more to you.
Rewards can create a different kind of fatigue if users treat them as the main reason to open the app. I would review benefits when making a relevant purchase, but I would not change spending habits simply to chase a reward. The app can help keep account-related value visible; it should not encourage purchases that would not otherwise make sense. That distinction is important for anyone who tends to confuse a benefit with savings.
For a family member who is uncomfortable with mobile banking, the app may require a little patience at first. I would recommend showing that person one routine—checking activity or reviewing a payment—rather than explaining every possible action in a single sitting. Narrow teaching works better than turning the app into a lesson about all of personal finance. Once the basic route is familiar, the app’s focused purpose becomes an advantage.
Barclays US compared with the usual alternatives
Compared with a desktop banking site, the app wins on immediacy. I can check an account from the same device I use when shopping, travelling, or receiving a purchase confirmation. A website may still feel better for a long review or for users who prefer a larger screen, but the app is more natural for short, repeated checks.
Compared with a multi-bank budgeting app, Barclays US wins on being the direct home for Barclays account information. That directness is valuable when I need to verify a specific transaction or account detail. The budgeting alternative wins when I want categories, combined balances, or a broader view across providers. I would not choose one expecting it to perform the other’s job equally well.
Compared with relying on email or text notifications alone, the app offers a more deliberate review point. Messages can be easy to miss, archive, or misunderstand. Opening the account encourages me to look at the surrounding activity instead of reacting to one isolated alert. Still, I would use notifications as prompts and the app as the place for confirmation, rather than depending entirely on either method.
The developer’s focus also matters. Barclays US is not an independent financial organizer attempting to connect every account a person owns. It is a provider-specific finance app, and that explains both its strength and its boundary. If you are already a Barclays customer, that specialization feels sensible. If you are not, there is little reason to install it simply because the app itself is free.
Who should keep it installed
I would keep Barclays US installed if I had an active Barclays account and wanted a reliable mobile checkpoint for purchases, payments, and account activity. Its lasting value comes from reducing uncertainty at ordinary moments: before a payment, after a purchase, or during a monthly review. Those moments are not exciting, but they are exactly where a finance app proves whether it belongs on a phone.
I would skip it as a primary tool if my main goal were detailed budgeting across several financial institutions, long-term planning, or a complete picture of household cash flow. In that case, a broader finance application would probably deserve the central place, with Barclays US kept only as a direct account companion if needed. Choosing the right tool by task prevents disappointment.
Its free price removes the usual subscription decision, but that does not make installation automatically worthwhile for everyone. The real question is whether direct Barclays access will change your behavior in a useful way. If it helps you review activity consistently and make payments with better awareness, it earns its place. If you rarely use the account or already have a routine that works well, the app may add little.
After the novelty fades, I judge the app less by how impressive the first launch feels and more by whether I still trust the routine it supports. Barclays US passes that test for its intended audience. It is focused, practical, and easy to justify as a recurring account-management tool, while its limited scope keeps it from replacing a full personal finance system. My lasting recommendation is simple: use it as a direct Barclays account checkpoint, not as your entire financial life.
For Barclays customers who want mobile convenience without turning every money task into a complicated project, I think it is worth keeping. The strongest results come from using it deliberately: review meaningful activity, check payment timing, examine recurring charges, and pair it with a separate budget when your finances extend beyond one provider. That is a sustainable role, and it is enough for this app to remain useful month after month.
FAQ
What is Barclays US, and what can I use the app for?
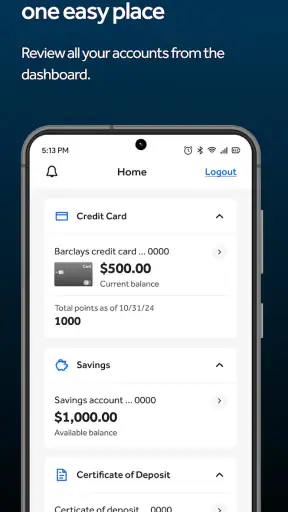
Barclays US is a mobile banking app for managing eligible Barclays credit cards and related accounts in the United States. After signing in, you can review balances, available credit, transactions, statements, payment due dates, and rewards information. Depending on your card, the app may also let you make payments, set up alerts, manage account preferences, and contact customer support without visiting the website.
Is the Barclays US app safe to use for banking and card management?
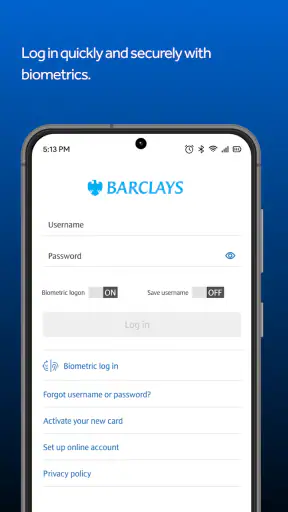
The app is designed with standard banking security features, including account authentication, encrypted connections, fraud monitoring, and options for device-based login such as fingerprint or face recognition when supported by your phone. However, security also depends on your habits. Download it only from the official app store, keep your operating system updated, avoid public Wi-Fi for sensitive activity, and never share passwords or verification codes.
Can I make payments and manage automatic payments through Barclays US?
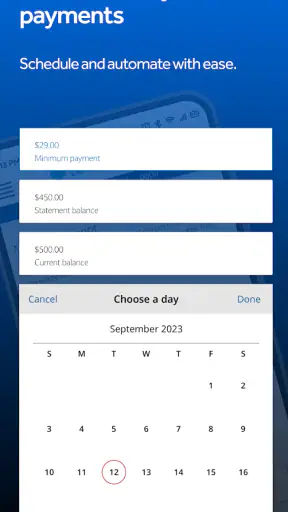
Yes, eligible cardholders can generally use Barclays US to make one-time payments from a linked bank account and review upcoming payment information. The available options may include scheduling payments, managing automatic payments, checking payment history, and viewing minimum or statement balances. Features can vary by account, and you should confirm the payment date and funding account carefully to avoid late payments or returned-payment fees.
Does Barclays US show rewards, transactions, statements, and account alerts?
The app provides a convenient overview of many account details, including recent purchases, posted payments, current balance, available credit, billing statements, and payment due dates. If your Barclays card includes a rewards program, you may also be able to view your rewards balance and redemption options. Alerts can help notify you about transactions, payments, and account activity, although exact features depend on your card.
What should I do if I cannot log in or notice suspicious activity in Barclays US?
If you cannot sign in, check your internet connection, verify that your login details are correct, and use the official password or username recovery options rather than repeatedly guessing. For suspected fraud, contact Barclays immediately through the number shown on the back of your card or within the official app. Do not respond to unexpected messages requesting login codes, and review transactions regularly for anything unfamiliar.


